
Two months after the largest IPO in history, SpaceX trades below its opening print even as its first public quarter makes the company easier to underwrite. That contradiction is why we believe SpaceX is a more important and future forward investment than Bitcoin at present valuations.
The market still tends to value SpaceX as a bundle of unusually ambitious projects: rockets, satellites, broadband, defense, artificial intelligence, data centers, payments, semiconductors and, eventually, off-planet infrastructure. Our post-Q2 model reaches a different conclusion. SpaceX is best understood as a vertically integrated system in which launch capacity builds connectivity and compute infrastructure, connectivity supplies distribution, and each business lowers the cost or expands the market of the others.
Dialectic’s Q2 SpaceX evaluation
Our model evaluates SpaceX through the physical operating data that measures the productive capacity of its integrated system. Q2 provides several important signals:
Revenue increased 92% year over year to $7.8 billion.
Adjusted EBITDA nearly tripled to $3.5 billion.
Starlink reached 12 million subscribers and continues to grow.
Nameplate compute capacity increased 3.5 times to 1.4 GW.
SpaceX signed $14.1 billion in cloud services agreements within 90 days.
The company ended the quarter with $100 billion in cash and marketable securities.
Blended fair value rises to $286/share (blended equity $3.93T), the Monte Carlo P50 to $314/share ($4.32T equity), with right-skew to $629/share ($8.64T) at P90 and a 10-year-horizon DCF of $368/share.
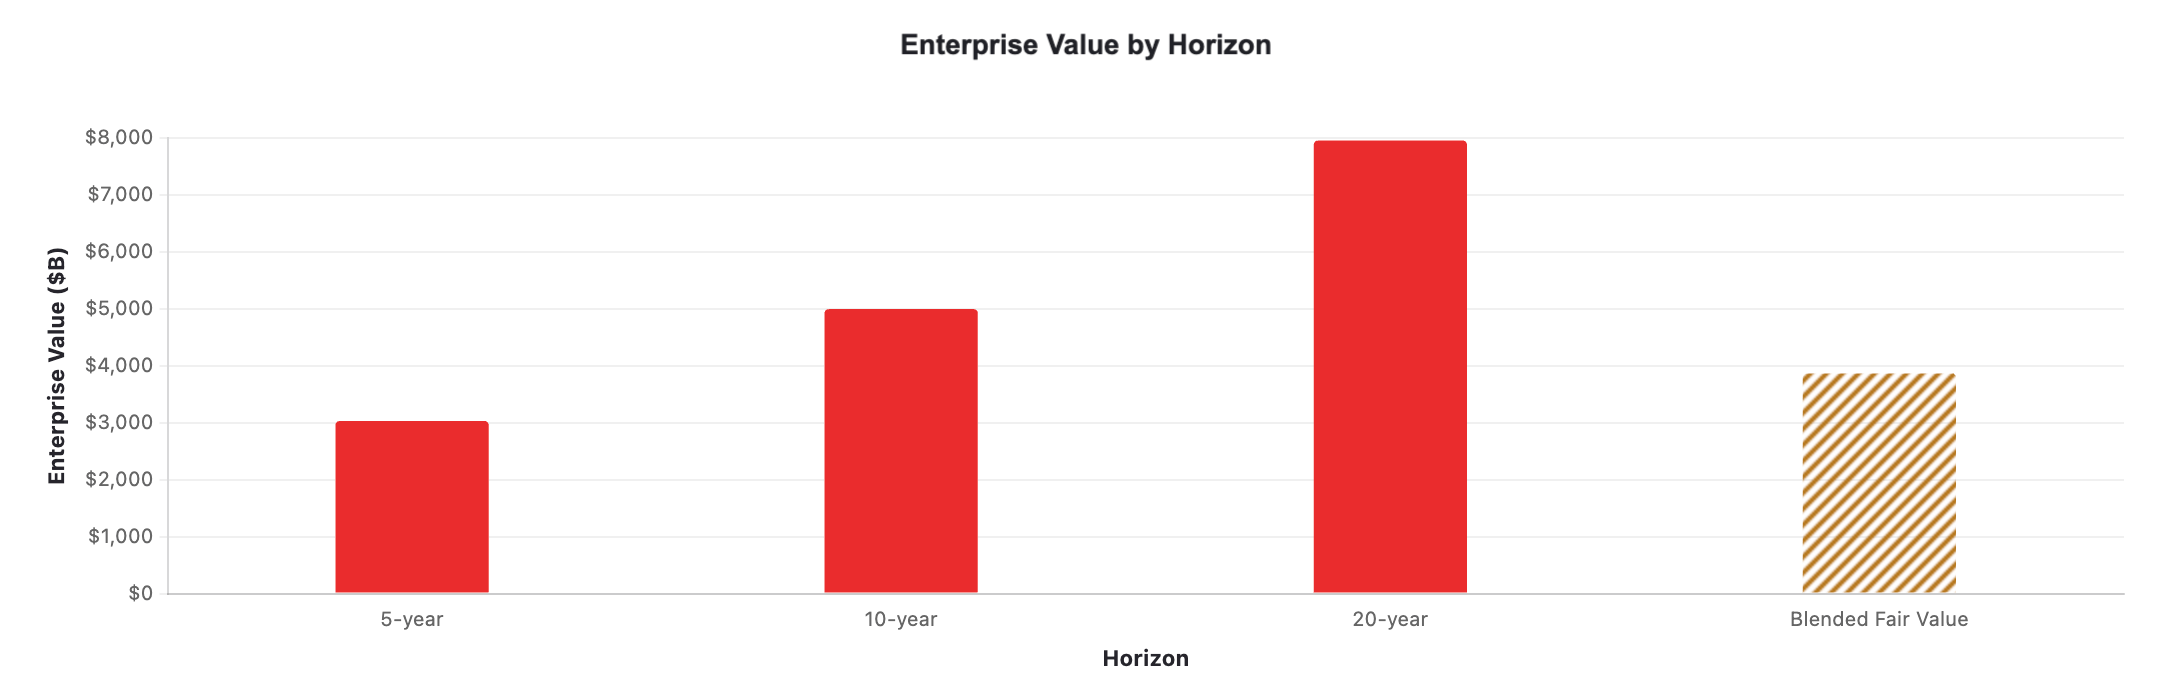
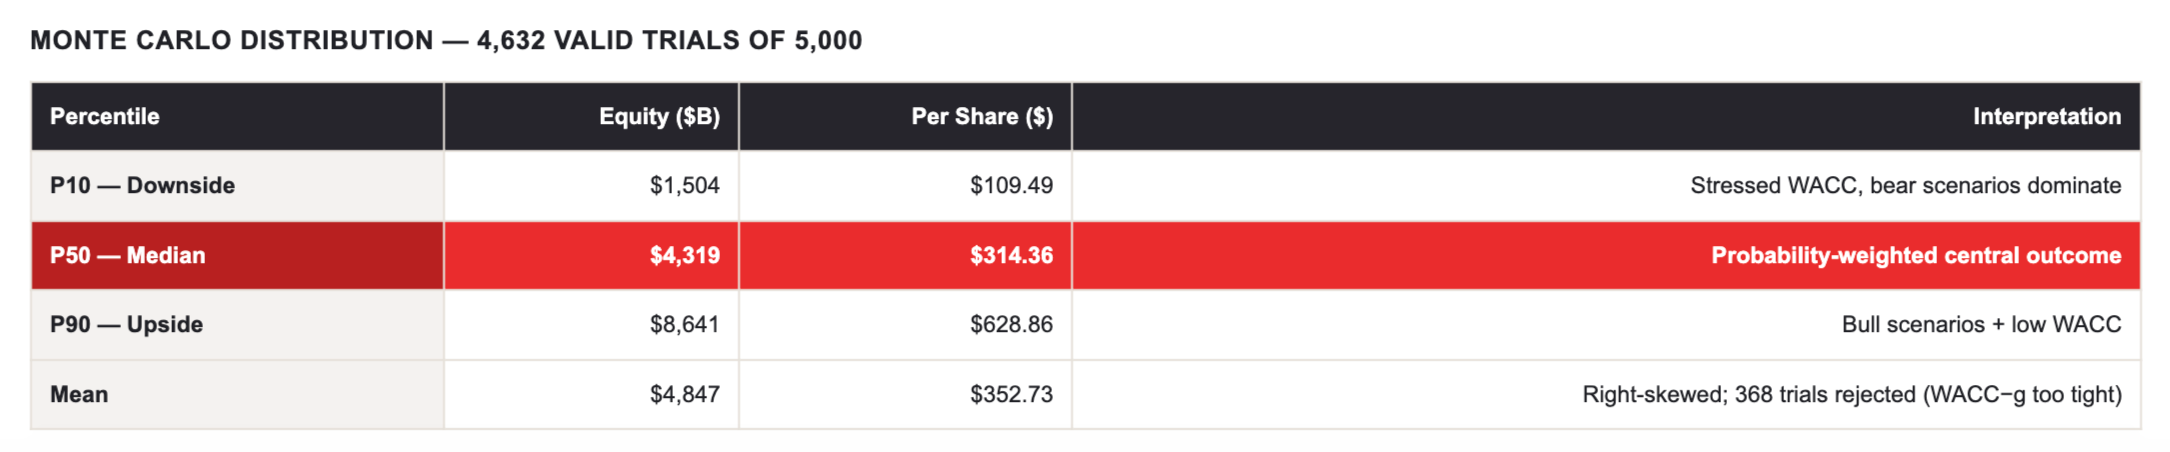
Our updated probability-weighted sum-of-the-parts model produces a blended fair value of $286 per share, while the Monte Carlo distribution reaches a P50 of $314 per share and a P90 of $629. At the current market (08/26/2026) price of $137.95 at the time of the memo, the gap is not primarily about whether SpaceX can describe an extraordinary future. It is about whether investors recognize what the company already operates today. For a deep dive on the pillars of our investment thesis, please review the pre-IPO analysis here.
Dialectic Starloop is the portfolio expression of this view: a new vault built on Makina’s infrastructure, launching on Base, Coinbase’s L2. It puts tokenized SpaceX exposure to work as collateral. The vault borrows dollars against the tokenized SpaceX position and deploys them into risk-adjusted onchain yield opportunities, so a position that would otherwise sit static in a wallet earns a dollar yield.
Q2 makes the flywheel visible
SpaceX now operates two toll roads. Competitors pay to reach orbit on its rockets, and AI companies pay to access compute in its data centers. In each case, counterparties help finance infrastructure that strengthens SpaceX’s own businesses.
Three businesses support the near-term thesis
The SpaceX story contains enormous optionality, but our updated valuation does not need Mars, asteroid mining or orbital data centers to carry the central case. The near-term thesis rests on launch, connectivity, and terrestrial compute.
Launch: Deflation is the moat
SpaceX delivers 1,041 tonnes to orbit in the first half of 2026 across 78 launches. Reusability and cadence continue to compress cost per kilogram. In most industries, falling unit prices threaten revenue. In launch, they expand the addressable market by making previously uneconomic missions possible.
This is a form of Jevons paradox: cheaper access to orbit increases the quantity demanded. As the cost curve falls, more satellites, defense systems, research payloads and commercial infrastructure become viable. Deflation strengthens the network rather than weakening it.
Connectivity: A global network with falling unit costs
Starlink reaches 12 million subscribers across 167 countries and generates $7.5 billion in first-half revenue. ARPU is broadly stable quarter over quarter even as the subscriber base doubles year over year. We read this as deliberate market expansion.
A terrestrial cell tower is a fixed investment in one geography. A satellite constellation distributes the cost of a global fleet across every additional customer. Each subscriber improves the economics of infrastructure that already covers the planet. Enterprise, aviation, maritime and direct-to-cell services extend the same network into higher-value markets.
Compute: The second toll road
The compute business is the least appreciated part of the current company. Nameplate capacity reaches 1.4 GW, up from 0.4 GW a year earlier, while contracted tenancy accelerates. The model values terrestrial data centers from installed capacity and market-clearing revenue per gigawatt rather than treating AI as a distant software option.
This matters because the market tends to separate SpaceX’s industrial capabilities from its AI economics. We see the opposite. The operational culture that learns to manufacture rockets, secure energy, build facilities and deploy infrastructure at high speed is precisely the culture required to scale compute. Hardware execution becomes an AI advantage.
SpaceX Tokenization: What it is and how it works
Launching soon, the Starloop vault accepts tokenized SpaceX exposure and uses it as collateral in onchain lending venues. Against that collateral, the vault borrows stablecoins within defined loan-to-value parameters and deploys the borrowed liquidity into onchain opportunities intended to earn more than the cost of financing. The risk-adjusted yield position is constantly monitored and rebalanced as collateral values, borrowing costs and available yields change.
The conceptual shift is simple:
A tokenized asset provides accessible economic exposure.
Managed collateral makes that exposure useful without requiring an outright sale.
Active onchain management seeks to capture the spread between financing cost and risk-adjusted yield opportunities.
Base provides a low-cost, high-throughput execution environment. Makina provides the non-custodial vault infrastructure, with permitted actions and risk parameters defined onchain. Dialectic Meccanico provides active strategy management.
SpaceX turns one productive asset into the foundation for another: rockets launch satellites, satellites distribute connectivity, data centers monetize power and engineering capacity. The vault applies a related logic at the portfolio layer by turning exposure into collateral and collateral into deployable liquidity, deployable liquidity into risk-adjusted yield.
Links:
SpaceX Thesis and Valuation Memo (Updated as of Aug 26, 2026)
Dialect/Base X Tokenized Stocks Launch Post on X
Let’s Chat in the Makina Telegram: Makina TG
Well done